What Is Behind the U.S. Dollar’s Rise and What It Means for Investors

Key takeaways
- The U.S. dollar has rebounded to its highest level since the 2025 “Liberation Day” tariff announcements, with the U.S. Dollar Index (DXY) now near 102.
- The main driver is higher U.S. interest rates, especially higher real (inflation-adjusted) yields, which attract global capital into dollar assets. The Fed’s return to rate hikes has added to that support.
- A stronger dollar makes imports and travel cheaper for Americans, but it can reduce returns on international investments when they are converted back to dollars.
- International stocks still trade at lower valuations than U.S. stocks, which supports keeping a balanced mix of domestic and international assets rather than reacting to currency swings.
One of the less-discussed consequences of interest rates reaching multi-decade highs is the notable strengthening of the U.S. dollar. The dollar’s value touches virtually every corner of financial markets, the economy, and daily life. It shapes the cost of imported goods, the affordability of international travel, the revenues of U.S. companies operating globally, and the performance of portfolios that hold international assets. The dollar is also sensitive to the outlook for U.S. economic growth, interest rate expectations, and concerns surrounding the national debt. In short, the dollar serves as a reflection of many of the forces driving global financial markets.
This is particularly relevant for long-term investors because the dollar has recently recovered to its highest level since last year’s “Liberation Day” tariff announcements. This rebound has been broad, with the euro, British pound, and Japanese yen all weakening as the dollar has strengthened. Higher Treasury yields are one of the most important reasons for this, with long-term interest rates such as the 10-year and 30-year Treasury yields at over 20-year highs. These trends also reflect the Fed’s shift to hiking policy rates again, which naturally raises shorter-term yields.1
While a stronger dollar carries certain benefits, its overall effects tend to be more nuanced. For consumers, a stronger dollar makes importing goods and traveling abroad more affordable. For businesses, however, it can reduce the competitiveness of U.S. exports in global markets. A rising dollar can also create a headwind for the returns on international investments, just as a falling dollar can provide a boost to those same returns.
So, what is driving the dollar’s recent strength, and what does it mean for investors?
Why is the U.S. dollar getting stronger?
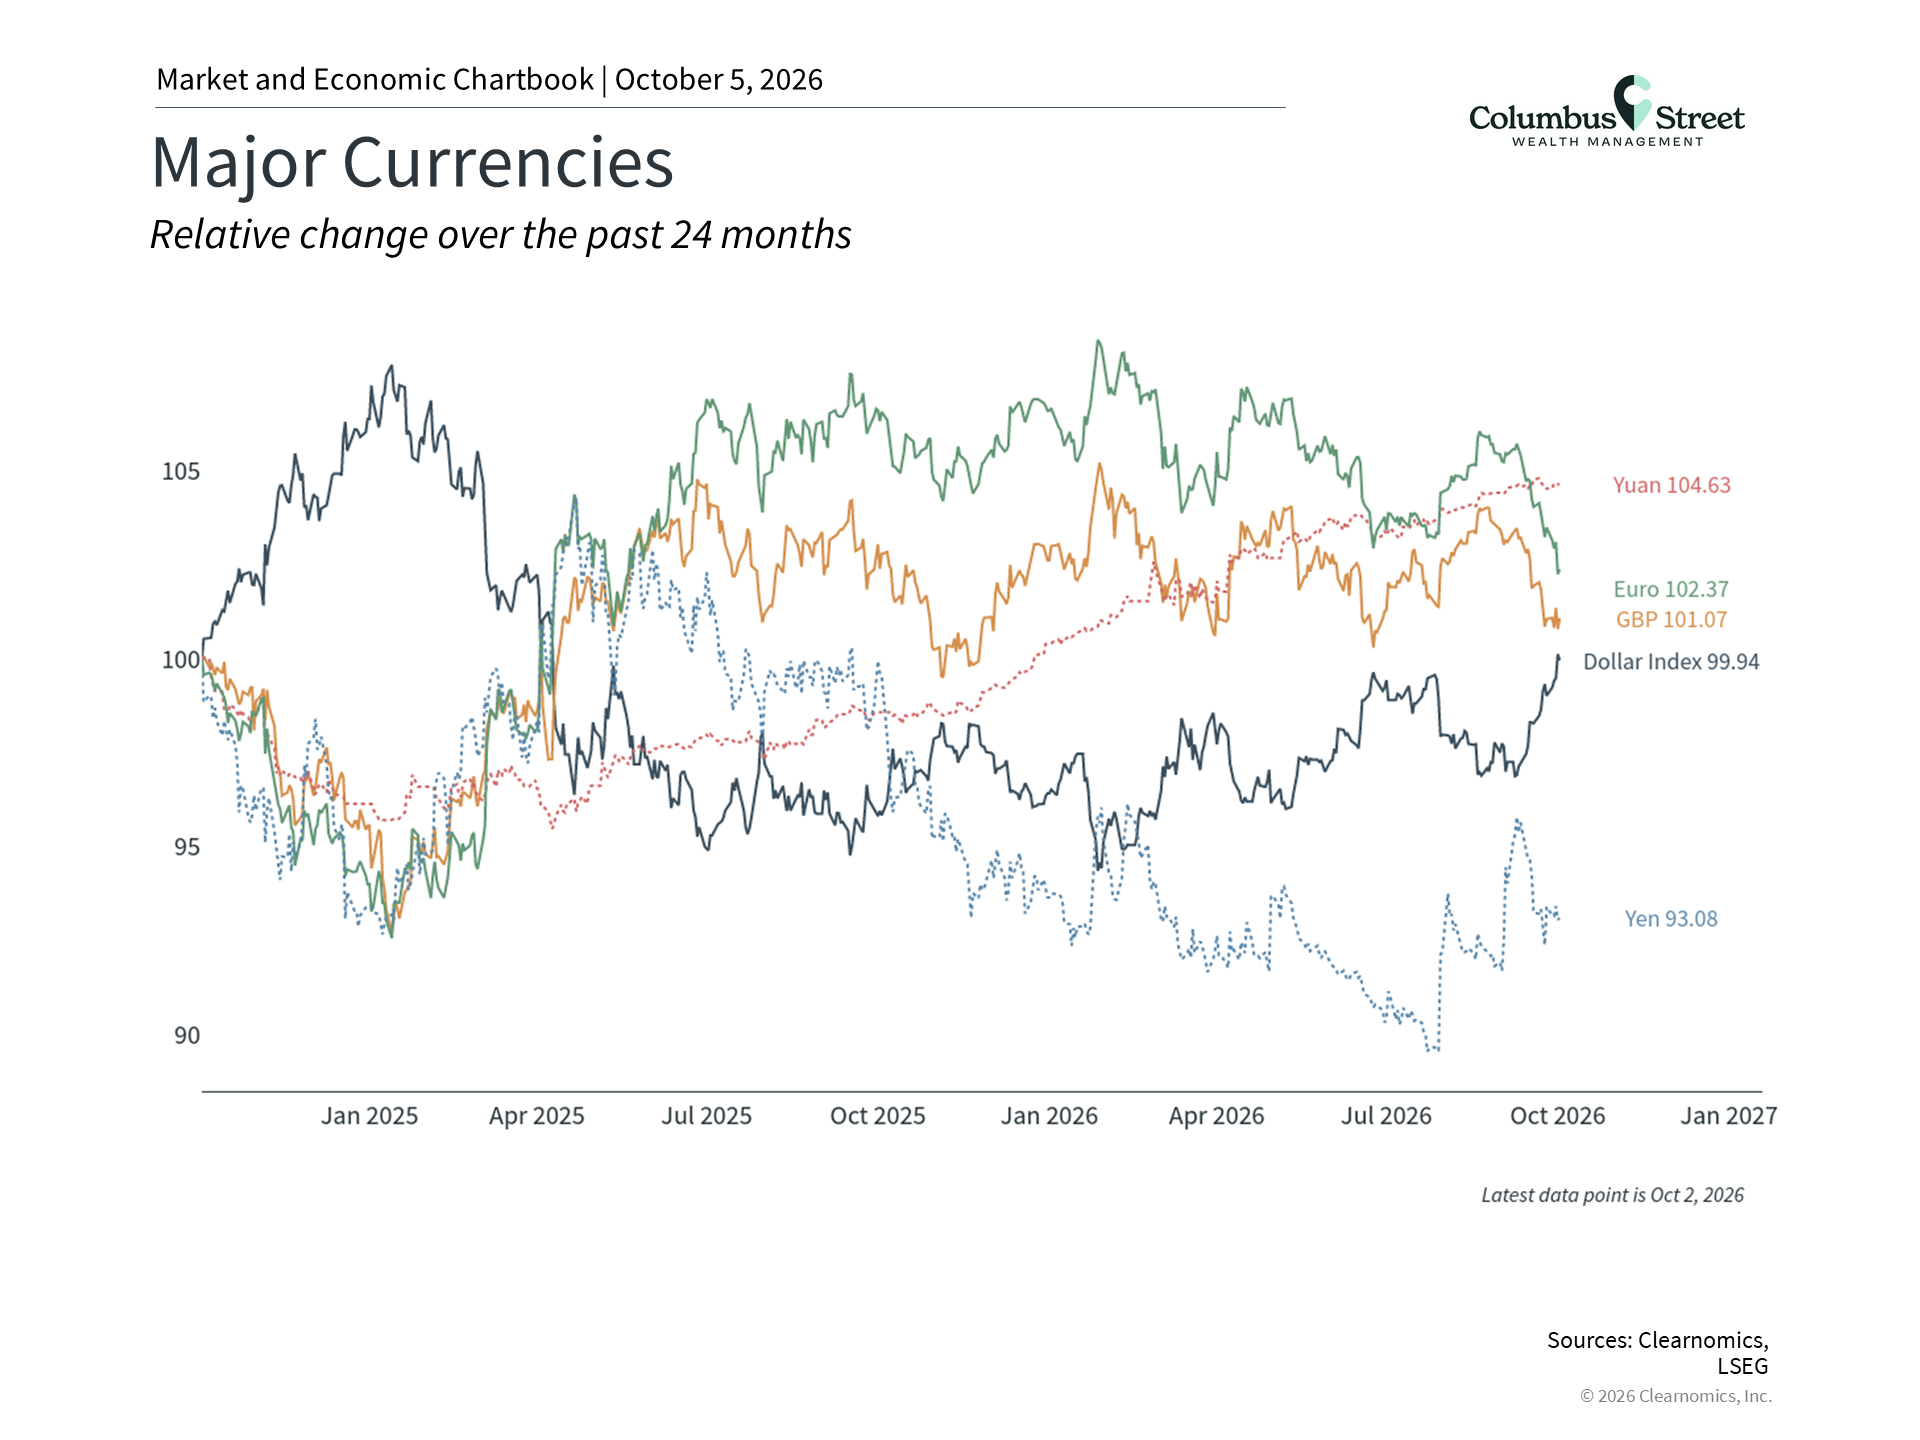
The dollar, as measured by the U.S. Dollar Index (DXY), which is based on a basket of six major foreign currencies, is now near 102 after hovering at or below 100 for the past year and a half. The chart above, which shows each currency’s value relative to its level two years ago, shows that the dollar is back to where it started after a period of weakness. Looking over a longer time horizon, current levels are among the strongest in nearly 25 years, with the exception of the peaks between 2022 to early 2025 when the index reached as high as 114.2
What has driven the dollar’s rebound? A key feature of global markets is that when U.S. interest rates rise relative to those in other countries, U.S. bonds and other assets become more attractive on a comparative basis. This concept is commonly known as the “carry trade.” In its simplest form, traders borrow in low-interest-rate currencies and deploy those funds into higher-yielding assets, such as U.S. Treasuries. This dynamic encourages capital to flow into dollar-denominated assets when yields are climbing, providing support to the dollar.
This is especially relevant today because the rise in U.S. rates is not just due to inflation, but because real, inflation-adjusted rates have increased. This means that the “true” return investors earn after accounting for rising prices has improved, which makes these yields even more attractive relative to those of other countries and regions.
That said, dollar movements are exceptionally difficult to predict, and they do not always simply follow interest rates. For instance, the dollar may experience sudden strength during periods of global uncertainty because it can serve as a safe-haven asset when investors seek stability. However, because the dollar reflects broad economic and global dynamics, it can be volatile when those trends are uncertain, as they have been over the past several years.
Does the national debt threaten the U.S. dollar?
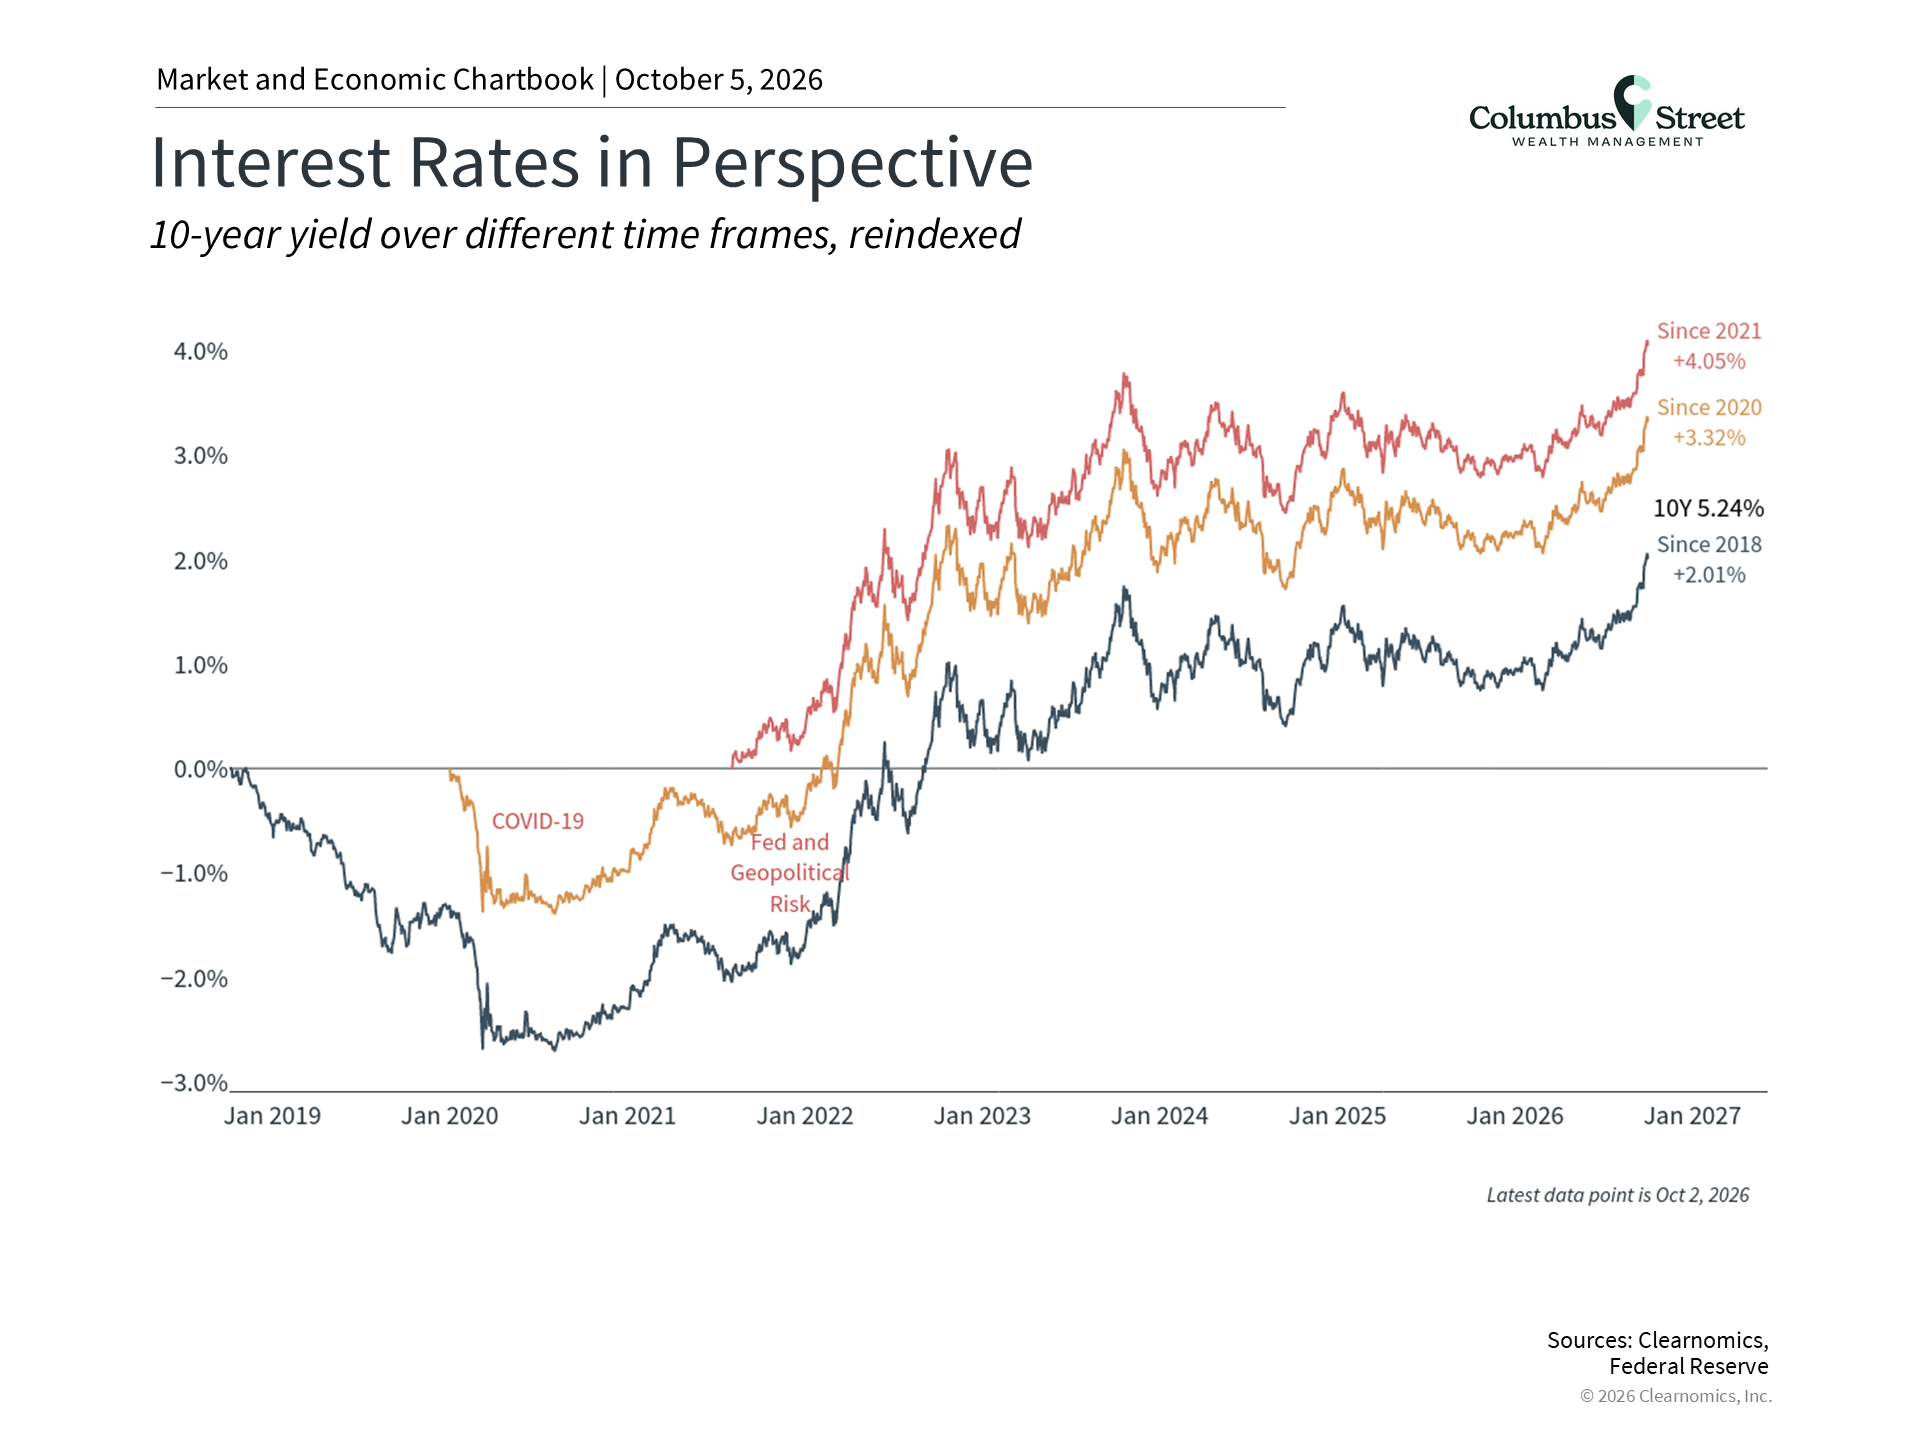
Another important dimension of the relationship between the dollar and interest rates is the influence of the national debt and persistent federal budget deficits. Because elevated debt levels can raise doubts about the government’s capacity and willingness to meet its financial obligations, this concern can naturally weigh on the dollar.
Rising interest rates, particularly the 10-year exceeding 5.3% and the 30-year around 5.7%, can worsen this situation because they raise the level of interest payments and make it more difficult for the government to roll over its debts, increasing the overall debt burden. In fact, part of the reason yields have risen may be due to concerns over the level of the debt and growing deficits.
It is therefore noteworthy that the dollar has strengthened despite these pressures, especially given reports that global central banks have at times shifted away from the dollar as the global reserve currency in recent years.3 A common question is whether there is a “breaking point” at which the debt becomes unsustainable. The reality is that this is untested, with the typical example being Japan which has operated with debt-to-GDP ratios well above 200% for decades.4
Other examples include Europe, where sovereign debt crises among the so-called PIIGS (Portugal, Italy, Ireland, Greece, and Spain) occurred regularly during the 2010s, ultimately requiring bailouts. Perhaps the biggest challenge is that fiscal sustainability does not appear to be a central focus in Washington at the moment.
Despite these issues, the United States still often acts as the lender of last resort and is where other countries and investors turn when global challenges arise. For example, the U.S. Treasury Department recently intervened in the foreign exchange market for the first time since the late 1990s to help Japan defend its currency.
From a portfolio perspective, history shows that placing too much emphasis on deficits when making investment decisions would often have been counterproductive. This is because deficits tend to be largest during crises, which is frequently when stocks are the most attractively valued. For example, deficits surged during the recessions around 2009 and 2020, periods that were followed by strong market recoveries.
How does a stronger dollar affect international investments?
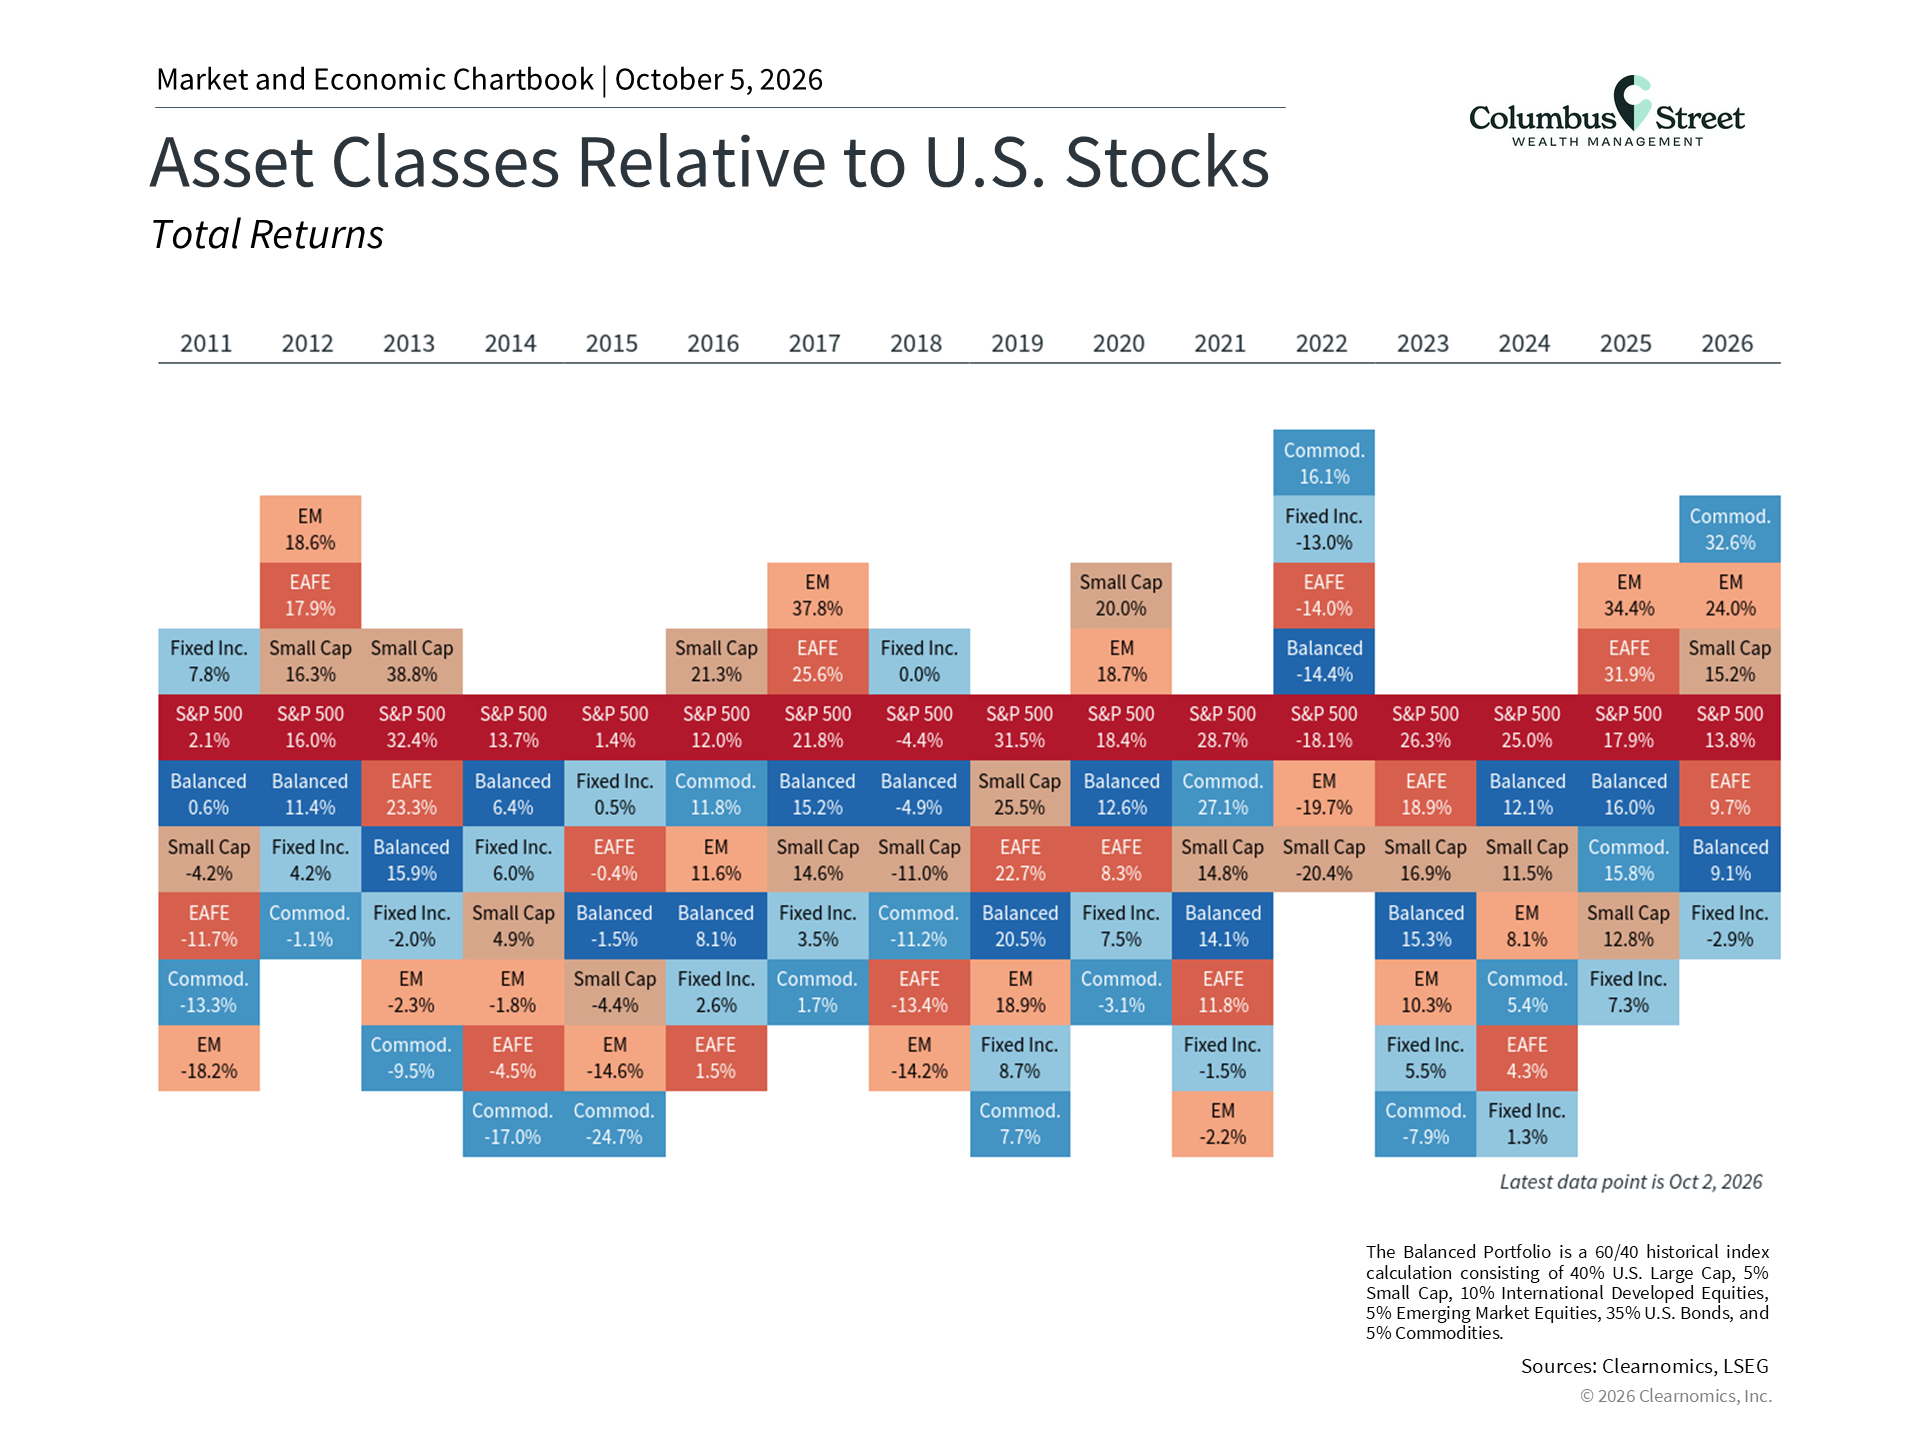
For investors, dollar movements matter because they can be a key component of international returns. When U.S.-based investors hold foreign stocks and bonds, those investments are denominated in local currencies that must eventually be converted back to dollars. When the dollar weakens, foreign investments are worth more in dollar terms, which boosts returns. The reverse is also true. The same principle applies to U.S.-based businesses that export to international customers, since a weaker dollar makes U.S.-made goods more affordable for those buyers.
This dynamic acted as a tailwind for diversified portfolios last year, when a weaker dollar helped support developed and emerging market returns. As the dollar has strengthened this year, this effect has reversed. For example, while emerging markets underperformed in the third quarter, they remain among the best performing asset classes so far this year.5
At the same time, currency movements are only one part of the picture. Fundamentals, including earnings and valuations, remain supportive across both developed and emerging markets, which has helped support the case for balanced portfolios. For example, the MSCI EAFE Index of developed market stocks and the MSCI EM Index of emerging market stocks currently have forward price-to-earnings ratios of 14.9x and 9.9x, respectively, compared to 19.2x for the S&P 500.6
Importantly, the dollar still remains the world’s dominant reserve currency. Concerns about whether this will continue to be the case are not new, and similar questions arose during Japan’s rise in the 1980s, after the introduction of the euro, amid China’s economic expansion, and more recently with the growth of digital currencies. In each case, the dollar retained its central role, although with shifts in assets held by global institutions.
The broader point for long-term investors is that currency movements are one of the many factors that affect portfolio returns. These movements can shift quickly in response to changes in interest rates, geopolitics, and economic expectations, as the past two years have shown. Rather than reacting to these swings, holding a balanced mix of domestic and international assets that are aligned with long-term goals is the best way to manage them.
The bottom line
The dollar has strengthened over the past year due to higher real interest rates and its role as a safe-haven asset, despite fiscal concerns. Investors should continue to stay balanced across regions as global trends impact the dollar and other currencies.
Frequently asked questions
Why is the U.S. dollar rising in 2026?
The dollar has strengthened mainly because U.S. interest rates, and especially real, inflation-adjusted rates, have risen relative to other countries. Higher yields draw global capital into dollar-denominated assets like U.S. Treasuries. The Federal Reserve’s return to raising rates and the dollar’s role as a safe haven during periods of global uncertainty have also added support.
What is the U.S. Dollar Index (DXY)?
The U.S. Dollar Index, or DXY, measures the value of the dollar against a basket of six major currencies: the euro, Japanese yen, British pound, Canadian dollar, Swedish krona, and Swiss franc. It is now near 102, after hovering at or below 100 for about a year and a half.
How does a strong dollar affect my international investments?
Foreign stocks and bonds are priced in local currencies that must be converted back to dollars. When the dollar strengthens, those investments are worth less in dollar terms, which can reduce returns. When the dollar weakens, the effect reverses and can boost returns, as it did for international stocks in 2025.
Does a stronger dollar mean investors should avoid international stocks?
Currency is only one part of the picture. Developed and emerging market stocks currently trade at forward price-to-earnings ratios of 14.9x and 9.9x, compared to 19.2x for the S&P 500, and emerging markets remain among the best performing asset classes this year. Because currency moves are difficult to predict, a balanced mix of domestic and international assets aligned with long-term goals is generally a more reliable approach than reacting to dollar swings.
Is the U.S. dollar losing its status as the world’s reserve currency?
The dollar remains the world’s dominant reserve currency. Similar concerns arose during Japan’s rise in the 1980s, after the euro was introduced, during China’s economic expansion, and with the growth of digital currencies. In each case the dollar kept its central role, though global institutions have shifted some of their holdings over time.
What does this mean for your plan?
Every client’s situation is different, and currency and interest rate shifts affect each portfolio in its own way. If you have questions about how a stronger dollar or higher rates could affect your international holdings or long-term goals, reach out to schedule a conversation. You can also learn more about our approach to fee-only, conflict-free planning or browse more market commentary in our Resource Library.
References
1. U.S. Department of the Treasury: Interest Rate Statistics
2. Clearnomics research using LSEG data, as of October 2, 2026
3. IMF Currency Composition of Official Foreign Exchange Reserves (COFER)
4. U.S. Treasury Fiscal Data: National Debt
5. Clearnomics research using MSCI data, as of October 2, 2026
6. Clearnomics research using LSEG data, as of October 2, 2026
Index Descriptions
S&P 500
The Standard & Poor’s 500 Index is a capitalization-weighted index of 500 stocks designed to measure performance of the broad domestic economy through changes in the aggregate market value of 500 stocks representing all major industries.
MSCI Emerging Markets Index
The MSCI EM (Emerging Markets) Index is a free float-adjusted market capitalization weighted index that is designed to measure the equity market performance of the emerging market countries of the Americas, Europe, the Middle East, Africa and Asia. The MSCI EM Index consists of the following emerging market country indices: Brazil, Chile, Colombia, Mexico, Peru, Czech Republic, Egypt, Greece, Hungary, Poland, Qatar, Russia, South Africa, Turkey, United Arab Emirates, China, India, Indonesia, Korea, Malaysia, Philippines, Taiwan, and Thailand.
MSCI EAFE Index
The MSCI EAFE Index is a free float-adjusted market capitalization index that is designed to measure the equity market performance of developed markets, excluding the U.S. & Canada. The MSCI EAFE Index consists of the following developed country indices: Australia, Austria, Belgium, Denmark, Finland, France, Germany, Hong Kong, Ireland, Israel, Italy, Japan, the Netherlands, New Zealand, Norway, Portugal, Singapore, Spain, Sweden, Switzerland and the UK.
Bloomberg U.S. Aggregate Bond Index
The Bloomberg U.S. Aggregate Bond Index is an index of the U.S. investment-grade fixed-rate bond market, including both government and corporate bonds.
DXY
The DXY is a U.S. dollar index based on a basket of currencies, including the Euro, Yen, Pound, Canadian Dollar, Swedish Krona and Swiss Franc.
All Content is information of a general nature and does not address the circumstances of any particular individual or entity. This Content is for informational purposes only; you should not construe any such information or other material as legal, tax, investment, financial, or other advice as a specific recommendation or specific endorsement by Columbus Street. The information in this document is provided in good faith without any warranty and is intended for the recipient’s background information only. Columbus Street accepts no responsibility for loss arising from the use of the information contained herein. In exchange for using this Content, you agree not to hold Columbus Street liable for any possible claim for damages arising from any decision you make based on information or other Content made available to you. You alone assume the sole responsibility of evaluating the merits and risks associated with using any information or other Content provided by Columbus Street before making any decisions based on such information or other Content. You should consult with your tax advisor and financial professional before making any determination as to the appropriateness of any planning strategy indicated herein.
Copyright (c) 2026 Clearnomics, Inc. All rights reserved. The information contained herein has been obtained from sources believed to be reliable, but is not necessarily complete and its accuracy cannot be guaranteed. No representation or warranty, express or implied, is made as to the fairness, accuracy, completeness, or correctness of the information and opinions contained herein. The views and the other information provided are subject to change without notice. All reports posted on or via www.clearnomics.com or any affiliated websites, applications, or services are issued without regard to the specific investment objectives, financial situation, or particular needs of any specific recipient and are not to be construed as a solicitation or an offer to buy or sell any securities or related financial instruments. Past performance is not necessarily a guide to future results. Company fundamentals and earnings may be mentioned occasionally, but should not be construed as a recommendation to buy, sell, or hold the company’s stock. Predictions, forecasts, and estimates for any and all markets should not be construed as recommendations to buy, sell, or hold any security, including mutual funds, futures contracts, and exchange traded funds, or any similar instruments. The text, images, and other materials contained or displayed in this report are proprietary to Clearnomics, Inc. and constitute valuable intellectual property. All unauthorized reproduction or other use of material from Clearnomics, Inc. shall be deemed willful infringement(s) of this copyright and other proprietary and intellectual property rights, including but not limited to, rights of privacy. Clearnomics, Inc. expressly reserves all rights in connection with its intellectual property, including without limitation the right to block the transfer of its products and services and/or to track usage thereof, through electronic tracking technology, and all other lawful means, now known or hereafter devised. Clearnomics, Inc. reserves the right, without further notice, to pursue to the fullest extent allowed by the law any and all criminal and civil remedies for the violation of its rights.
Keep more of what you earn. Do more of what you love.
Want to know more? Get in touch.
*Please do not send any financial information