Q4 2026 Market Outlook: Navigating Higher Rates, Record Market Levels, and Fed Policy Shifts
Key takeaways
- U.S. stocks finished Q3 2026 near all-time highs. The S&P 500 returned 2.3% for the quarter and 12.7% year-to-date, even as the 10-year Treasury yield climbed to 5.29%, a two-decade high.
- The Federal Reserve raised rates for the first time in three years, to a range of 3.75% to 4.00%, largely in response to higher energy prices.
- Gains came from many places, including energy, developed international stocks, and commodities. That breadth is a reminder of the value of a balanced portfolio.
- History shows the S&P 500 has averaged 8.6% annual total returns in midterm election years since 1933, so political headlines are not a reason to abandon a long-term plan.
The third quarter presented investors with a mixed environment shaped by two significant forces. Interest rates climbed to 20-year highs, while strong corporate earnings continued to provide meaningful support for equities. Against this backdrop, oil prices rose back above $100 per barrel, the Federal Reserve raised rates for the first time in three years, and attention turned toward AI developments and the approaching November midterm election.
In spite of these crosscurrents, major U.S. stock indices finished the quarter near their all-time highs. Notably, these gains were not confined to a single corner of the market. The energy sector, developed market equities, and commodities all made meaningful contributions to portfolios during the quarter. And although bonds have faced headwinds as rates have risen, bond yields are now at their most attractive levels in recent memory.
These market dynamics serve as a reminder that maintaining portfolio balance is essential to navigating shifting market conditions, particularly when those conditions create opportunities for long-term investing and financial planning. With that in mind, how can investors remain well-positioned as these themes continue to play out in the fourth quarter?
What happened in markets in Q3 2026?1
- The S&P 500 returned 2.3% in the third quarter with dividends and the Nasdaq Composite gained 2.6%, while the Dow Jones Industrial Average declined -2.3%. Year-to-date, the three indices have returned 12.7%, 16.1%, and 7.2%, respectively.
- Developed market international stocks (MSCI EAFE) gained 0.9%, while emerging market stocks (MSCI EM) declined -0.4% over the quarter, both in U.S. dollar terms.
- The Bloomberg U.S. Aggregate Bond Index fell -3.5% in the third quarter for a year-to-date decline of -2.9%, with longer-dated bonds struggling. The 10-year Treasury yield climbed to 5.29%, a two-decade high.
- The Bloomberg Commodity Index jumped 15.1% over the quarter. Brent crude ended the quarter at $103 per barrel while WTI finished at $90.
- Gold fell further to $4,156 per ounce, while the U.S. Dollar Index recovered to 101.45.
- August headline Consumer Price Index (CPI) rose 3.4% year-over-year, while core CPI, which excludes volatile food and energy prices, increased only 2.4%. The core Personal Consumption Expenditures (PCE) price index, the Fed’s preferred measure of underlying inflation, rose 3.0% year-over-year in August.
- The Federal Reserve raised its key policy rate to a range of 3.75% to 4.00% in September.
- The third estimate of second quarter Gross Domestic Product (GDP) showed that growth was better than expected at 2.2% quarter-over-quarter. This was primarily driven by a 2.5% gain in personal consumption expenditures.
Why are interest rates at 20-year highs, and what does it mean for investors?
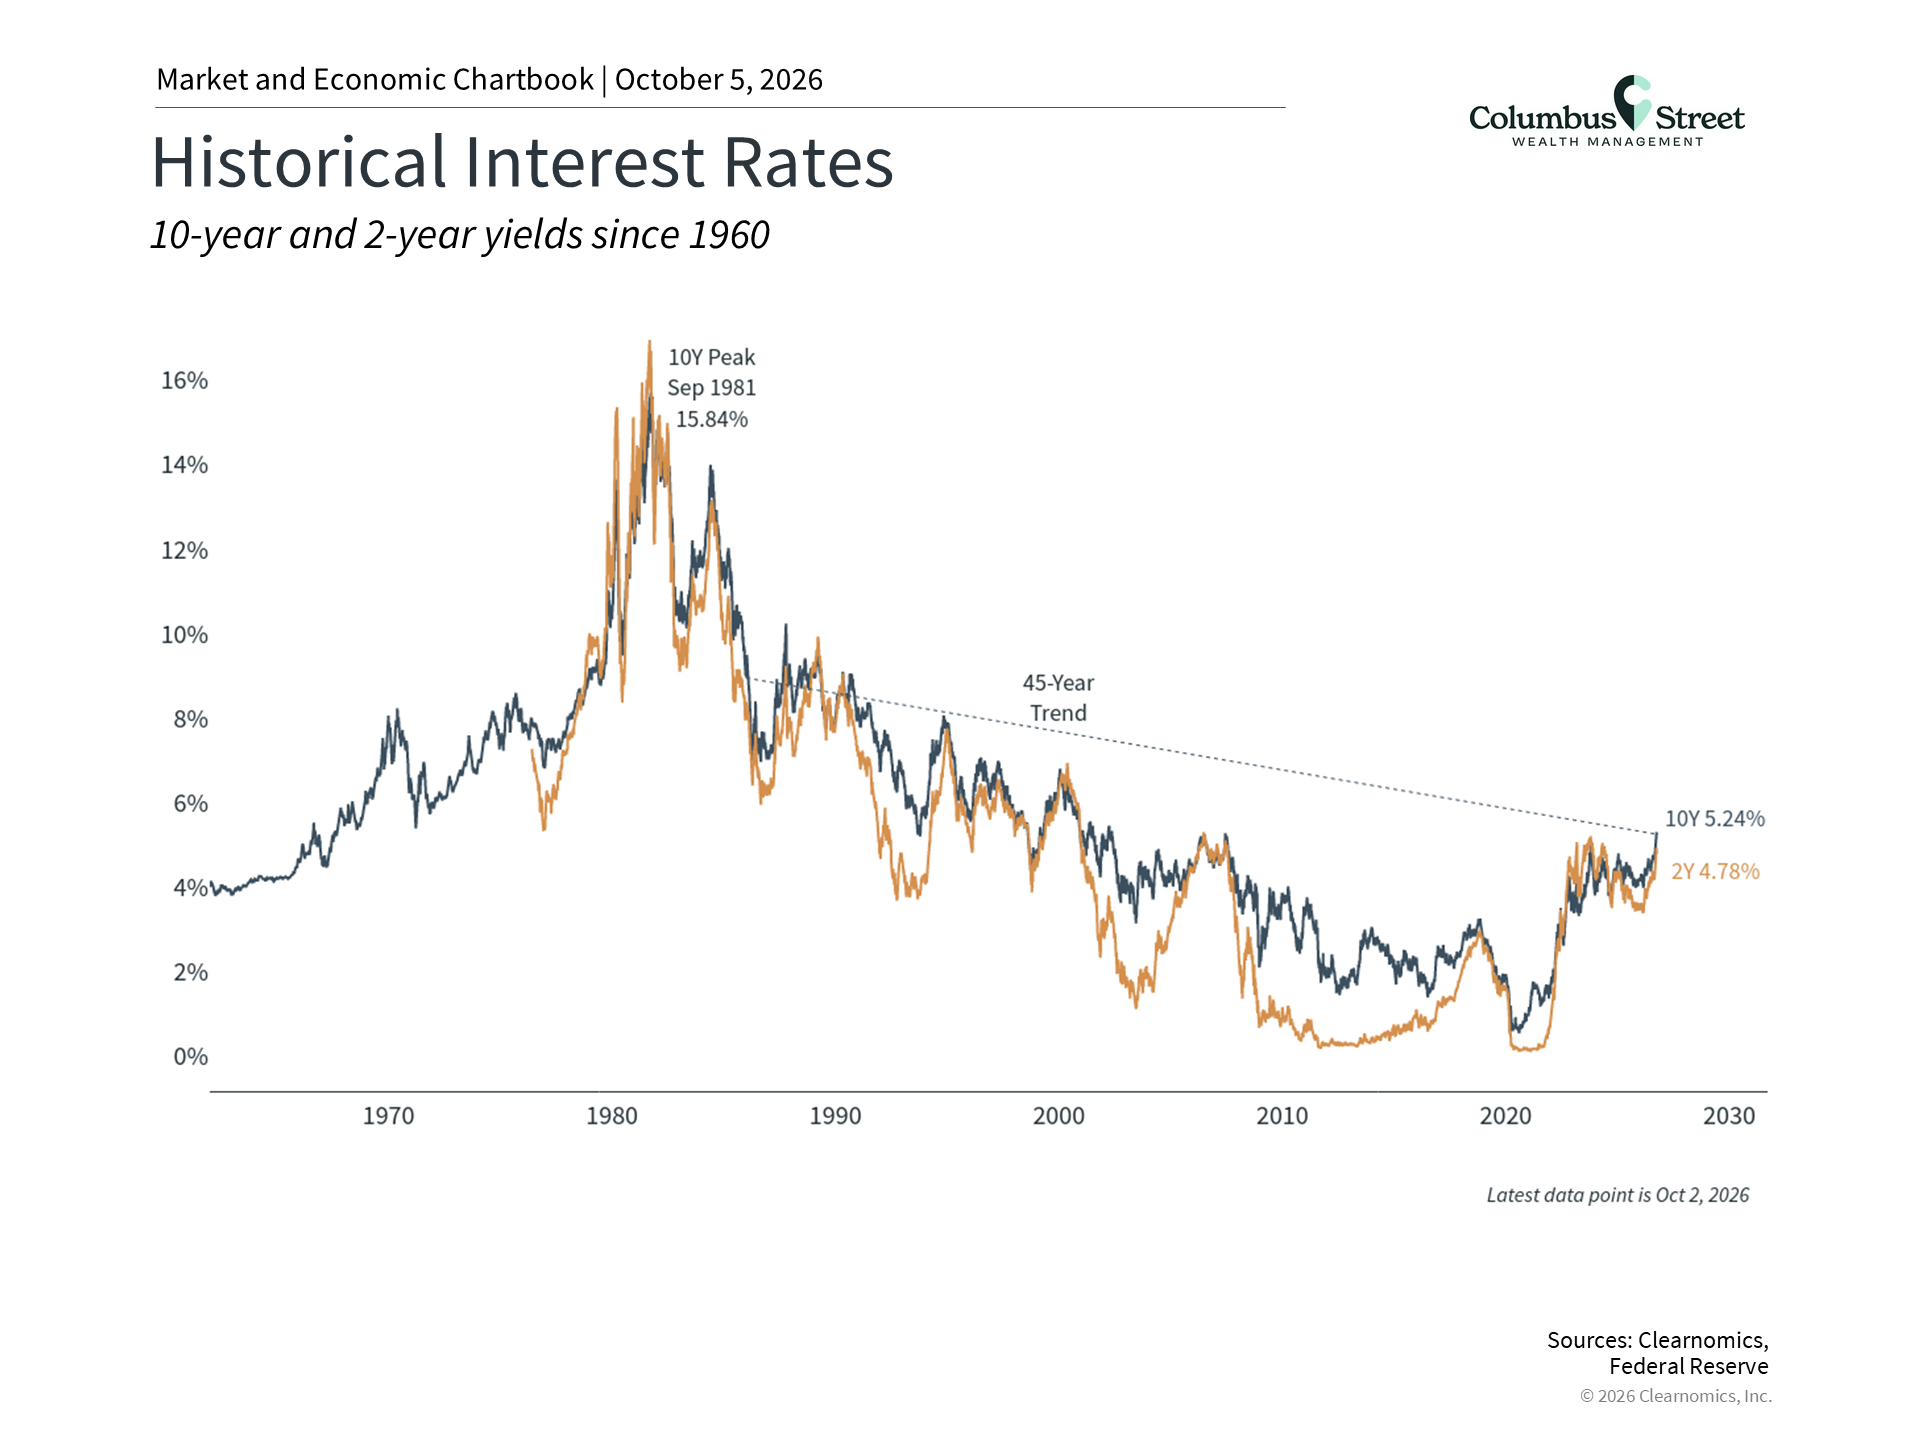
The most defining feature of the third quarter was the steady rise in interest rates to levels not seen since the early 2000s. For long-term investors, this is significant because the low-rate environment that followed the 2008 global financial crisis is no longer the primary driver of portfolio decisions. The ability of bonds to generate more meaningful income today has become an important factor in asset allocation considerations.
A historical perspective on interest rate trends is useful here. From their peak in the early 1980s through 2020, rates experienced a long and gradual decline, punctuated by shorter-term fluctuations tied to the business cycle and economic events.2 This period is often called a 40-year bull market in bonds, as falling rates made existing bonds more valuable, benefiting portfolios and supporting broader economic activity.
Elevated interest rates ripple through other areas of the economy as well, with the housing market being a prominent example. According to Freddie Mac, the average 30-year fixed-rate mortgage has moved back above 7% after approaching 6% at the start of the year.3 This dynamic has given rise to what economists describe as the “lock-in” effect, where homeowners who locked in low rates in prior years have little incentive to sell, dampening overall housing market activity.
Of course, interest rates are inherently difficult to forecast and can shift quickly, particularly given ongoing uncertainty in oil markets and the labor market. Nevertheless, the fact that rates are hovering near multi-decade highs represents a meaningful development for investors to keep in mind.
Why did stocks reach record highs even as rates rose?
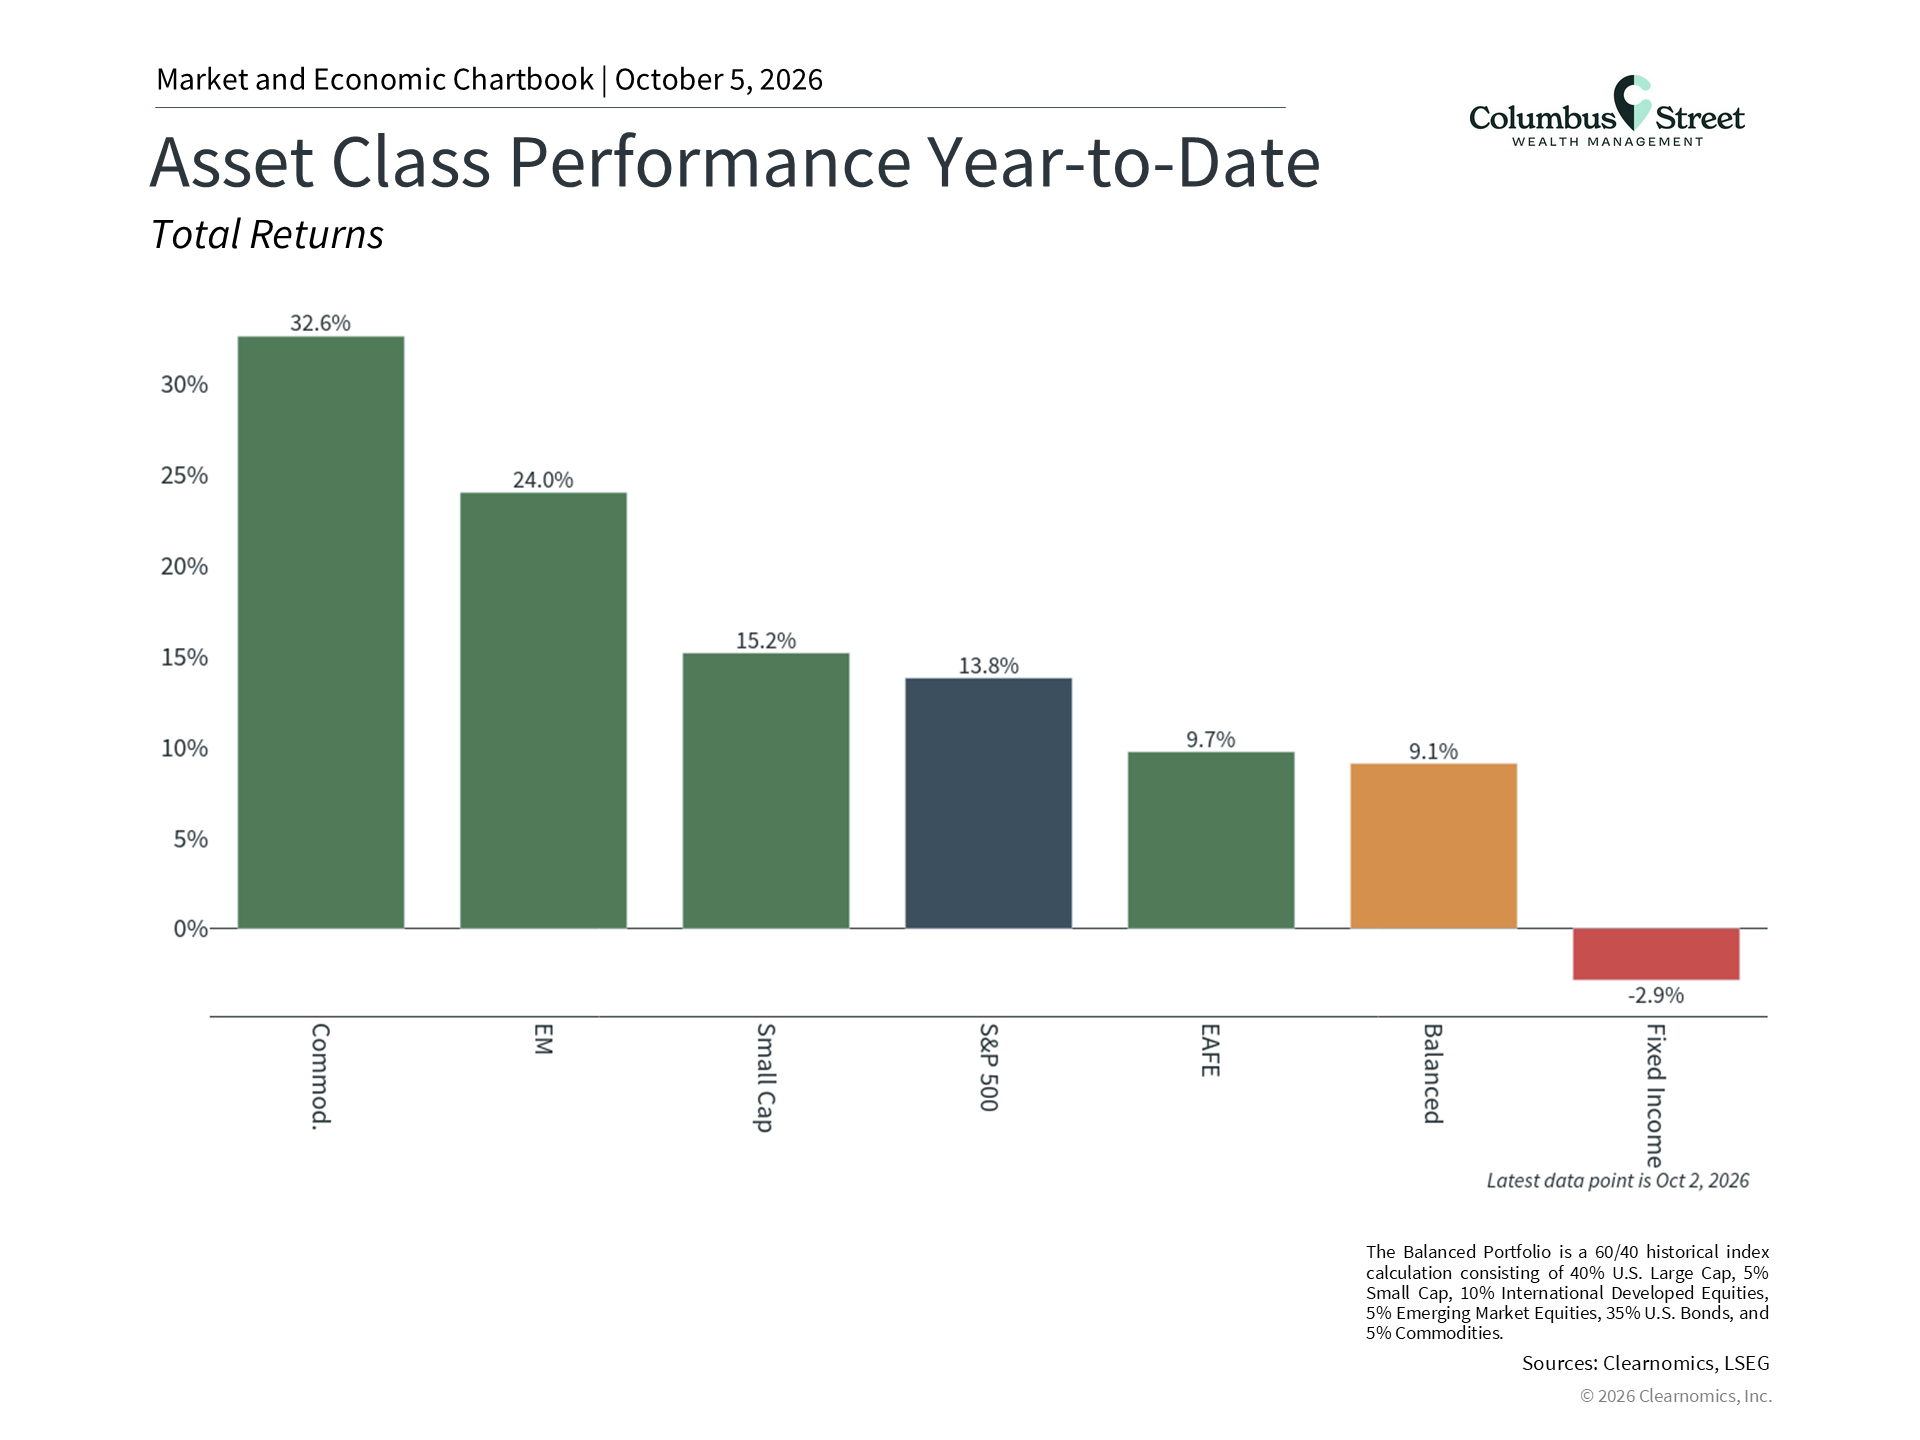
Notwithstanding recurring bouts of short-term uncertainty, the S&P 500, Nasdaq, and Dow Jones Industrial Average each reached new all-time highs during the third quarter. This performance reflects the dual support of a resilient economy and structural trends such as AI infrastructure investment, which have bolstered corporate profitability. Current consensus estimates suggest that S&P 500 earnings growth for the next twelve months could exceed 30% across 2026.4
This year’s positive performance has not been limited to U.S. large cap equities. Small cap stocks, while facing pressure in the third quarter, have still outperformed on a year-to-date basis, in part because many of these companies play key roles in the AI supply chain. Other regions have also benefited from AI-related trends, particularly semiconductor companies across Asia, which has provided some support to the MSCI Emerging Markets index, even as that index posted a decline in the third quarter.5
Commodities have also added to portfolio returns, driven by different factors. Ongoing conflict in the Middle East pushed oil prices from around $70 per barrel in early July to above $100 by September. Copper reached a new all-time high amid mine supply deficits and structural demand from AI infrastructure buildout, while diesel hit a record due to severely constrained global refining capacity.
The breadth of contribution across asset classes underscores the value of a thoughtfully constructed asset allocation. That value will only grow as the fourth quarter brings continued focus on monetary policy, Treasury yields, and oil prices.
Why did the Fed raise interest rates in September 2026?
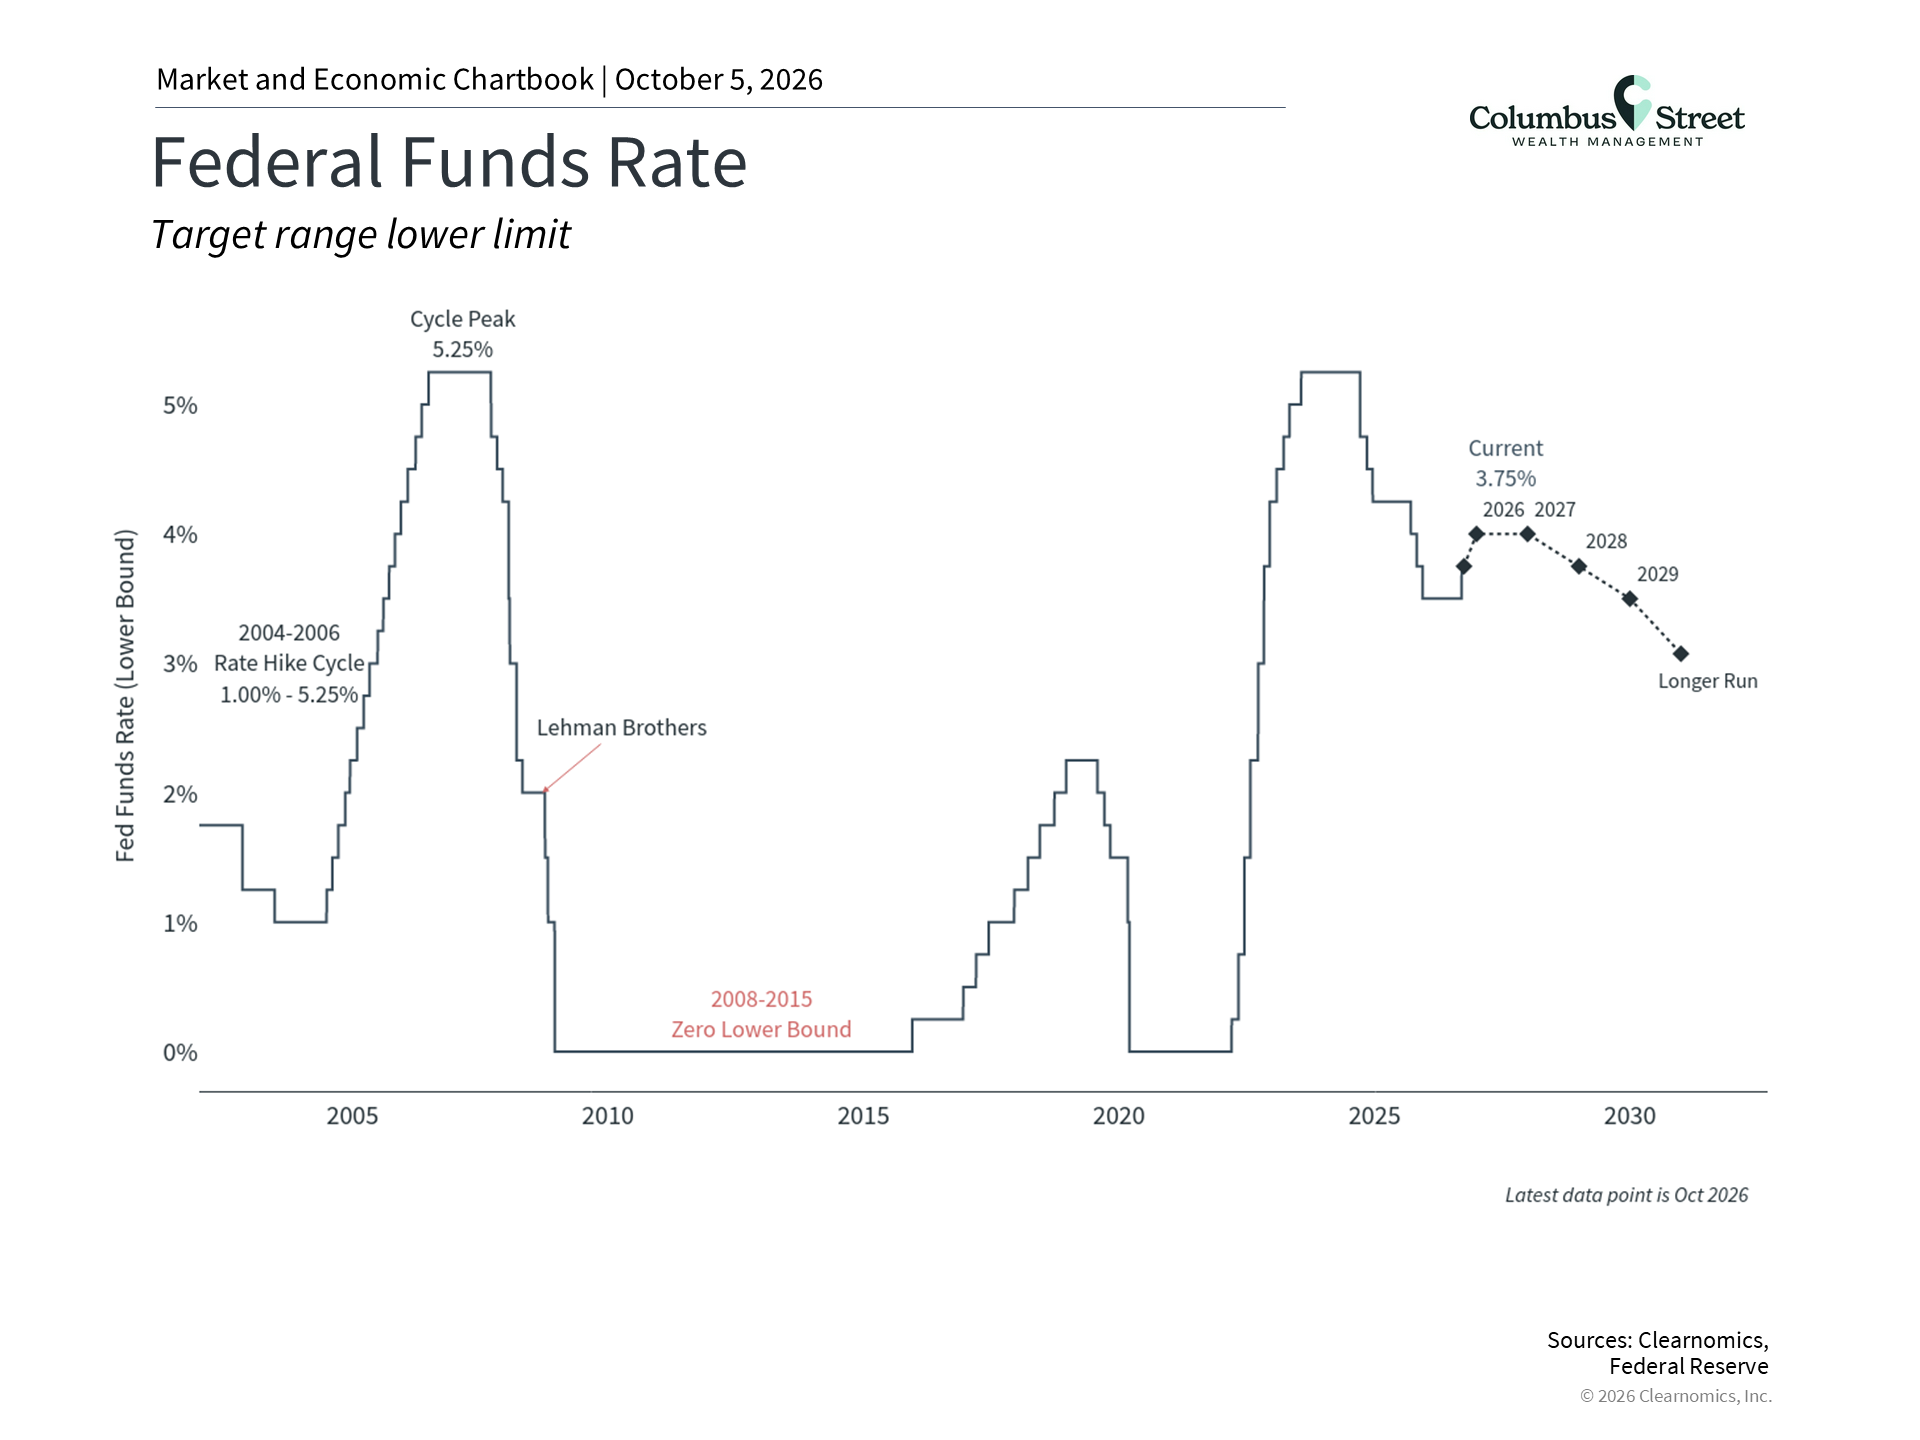
At its September meeting, the Federal Reserve raised policy rates by one-quarter of a percent, bringing the target range to 3.75% to 4.00%. This marked the first rate increase in three years, following a series of rate cuts that ran from September 2024 through December 2025, as illustrated in the chart above. Markets had priced in over a 90% probability of this move ahead of the meeting, and while there were some immediate fluctuations following the announcement, the broader market absorbed the decision without significant disruption.6
What sets this hike apart from prior tightening cycles is that the Fed is largely responding to higher energy prices. Economists refer to this dynamic as “cost-push inflation,” a scenario in which supply disruptions drive prices higher. While the Fed cannot address geopolitical events through interest rate policy, it can work to prevent elevated energy costs from feeding through into other inflation categories that affect consumers and businesses.
Projections from Fed officials currently suggest the central bank may raise rates once more before year-end, followed by a pause through 2027 and only a gradual easing thereafter. These projections are subject to revision as economic conditions evolve, so they should be interpreted with appropriate caution.
It is understandable that some investors view tighter monetary policy as a headwind for markets. In practice, the impact depends heavily on the reasons behind the rate increases. Historically, it is not uncommon for markets and interest rates to rise together, particularly later in the business cycle when growth, corporate earnings, and capital investment remain healthy. The third quarter offers a recent illustration of this, with major indices reaching record levels even as rates climbed. Monetary policy is, of course, only one of several forces that will shape the months ahead, with the political calendar also playing a role.
How do midterm elections affect the stock market?
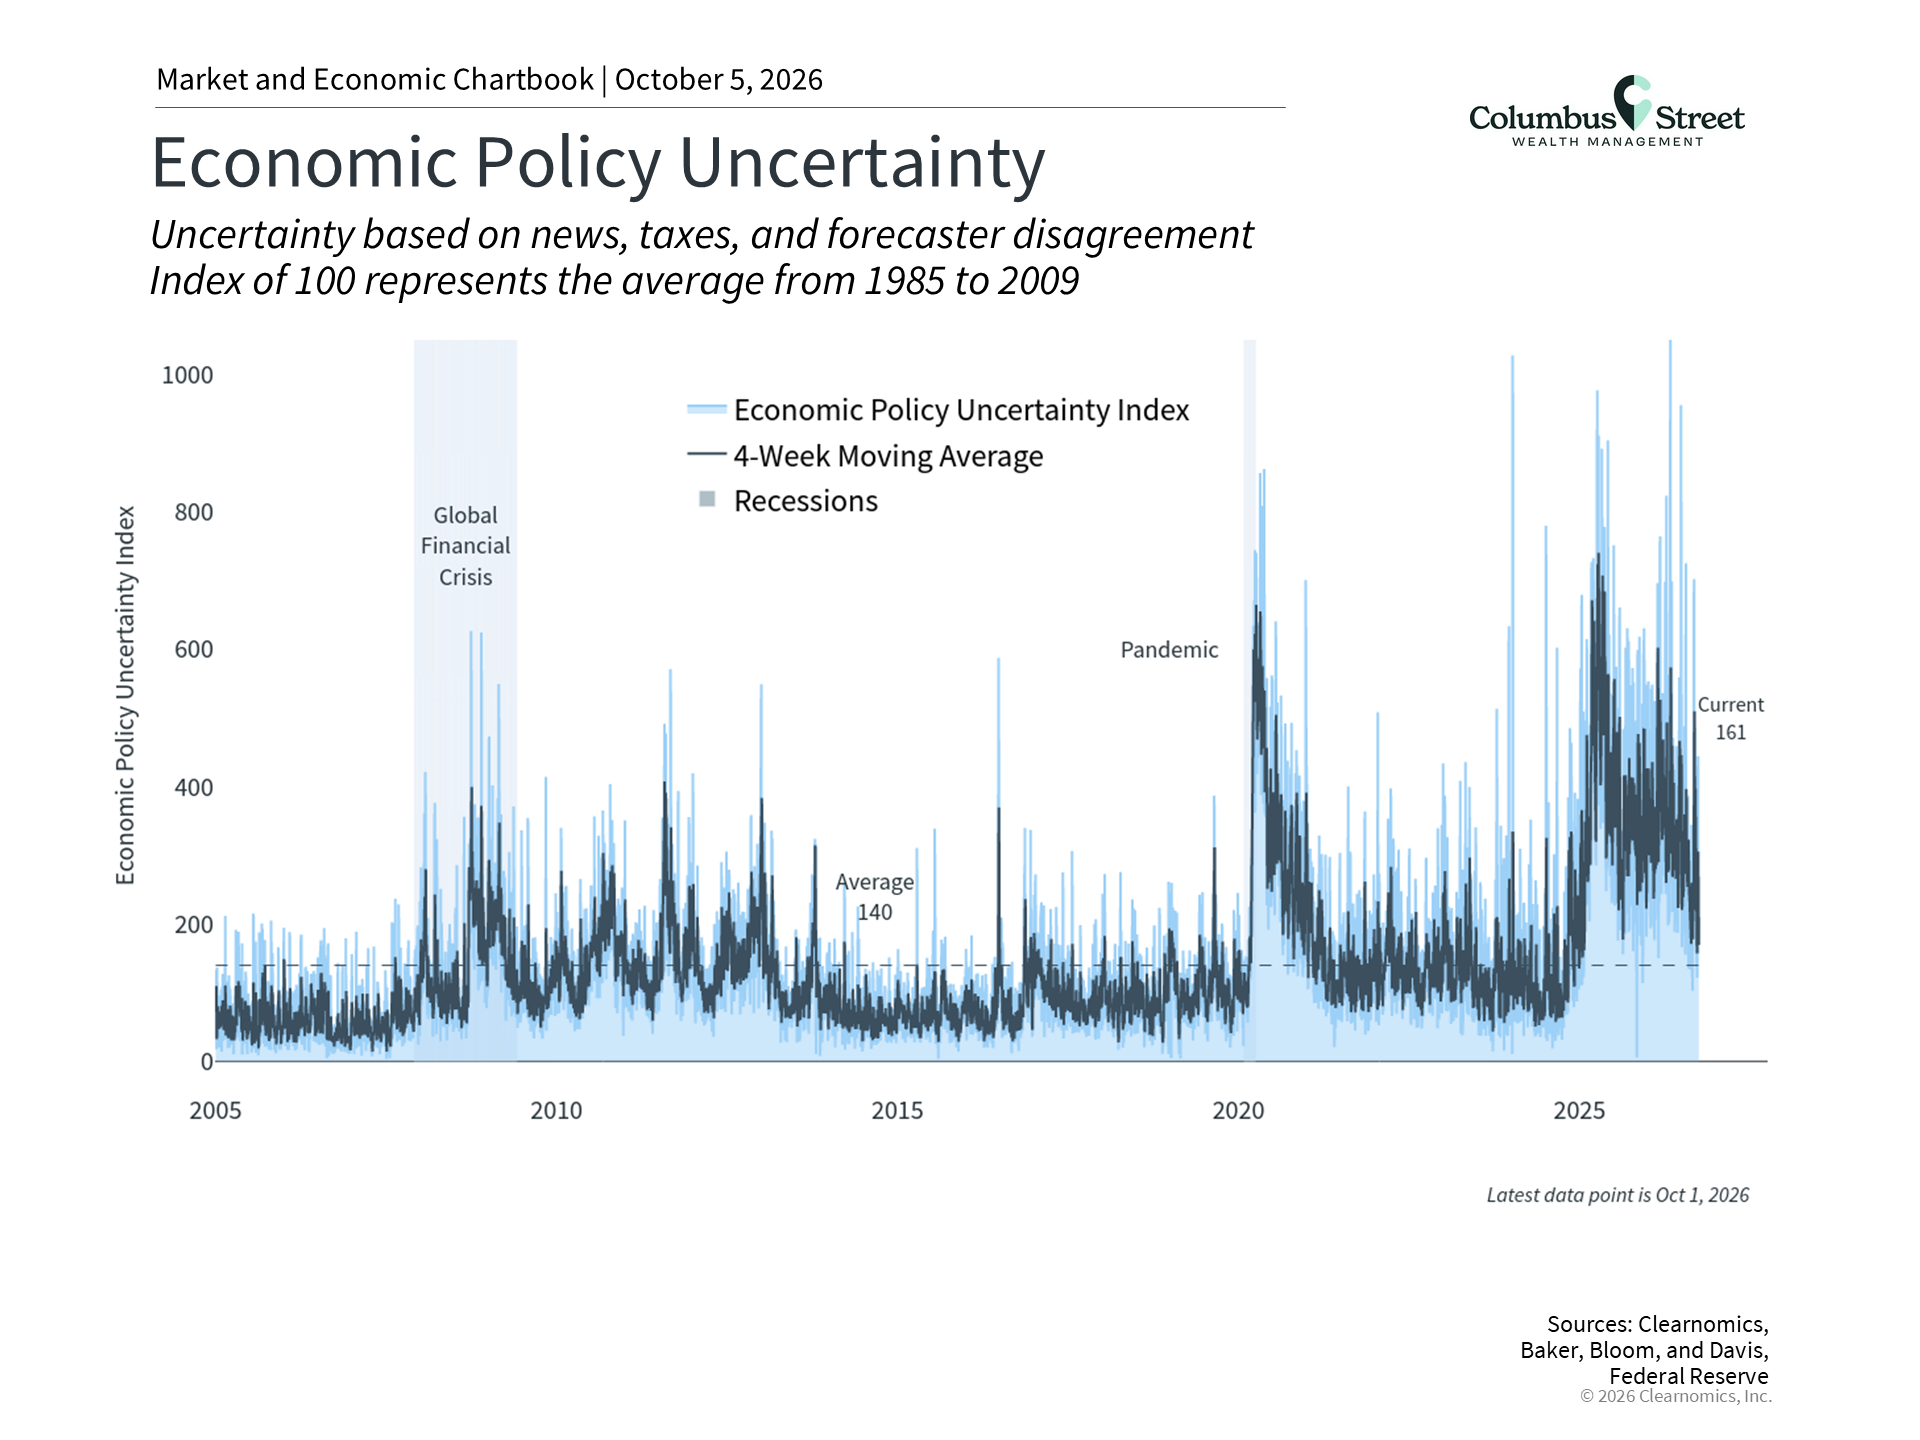
As citizens, voters, and taxpayers, elections are among the most consequential events in public life. They determine the direction of policy across areas such as entitlement programs, taxes, and the federal debt, and they give expression to the values that inform new legislation. When it comes to investing, however, it is important for investors to avoid making portfolio decisions based on political preferences.
This November’s midterm election is unfolding against a complex backdrop that includes tariffs, geopolitical conflict, inflation, and questions surrounding AI. As the chart above illustrates, economic policy uncertainty has been elevated over the past two years, contributing to periods of short-term market volatility. At the same time, markets have also demonstrated their ability to stabilize and recover in ways that can catch investors off guard. While past performance is no guarantee of future results, it remains important not to overreact to short-term political headlines.
More broadly, it is natural to assume that politics drive the stock market, or that election years tend to be more volatile. History suggests otherwise. In fact, the S&P 500 has averaged annual total returns of 8.6% in midterm election years since 1933.7 History also shows that markets have generally performed well across various configurations of Congress. It is not unusual for the sitting president’s party to lose its majority during midterm elections, as was the case under Biden, Trump’s first term, Obama, and Clinton, among other recent examples.8
Beyond questions of congressional control, other sources of political uncertainty remain on investors' minds. Chief among them is the size of the national debt and the annual budget deficit. Total federal debt recently surpassed $40 trillion for the first time, equivalent to nearly $120,000 per American.9 The annual budget deficit is also projected to exceed $2 trillion for the government’s 2026 fiscal year.10 Over time, these trends could push up borrowing costs for the government and increase the annual interest burden it must carry.
While many of these challenges are genuine, the key for investors is to distinguish between what they can and cannot control. Holding a portfolio constructed to perform across a range of economic and political environments is far more important than attempting to predict the outcome of any single election or the precise level of next year’s deficit.
Is the stock market too dependent on AI and technology stocks?

AI and related technology trends have been among the most powerful forces shaping market performance over the past decade. Beyond driving returns for groups such as the Magnificent 7, these themes have directly influenced the fundamental earnings trajectory across sectors. The chart above, for example, highlights the divergence in earnings growth between Information Technology and the other ten S&P 500 sectors.11
This “concentration risk” is a concern for some investors who worry that the market has become overly reliant on a handful of stocks. While many technology-related segments of the market continue to perform well, other sectors have also contributed to healthy returns over the past year. These sectors are posting above-average earnings growth, which underpins their stock prices. The energy sector, for instance, has benefited from higher oil prices and stands as the best performing sector with a 37.4% year-to-date gain through the third quarter.
Much of the AI-driven growth is linked to infrastructure buildout, including data centers. One of the most important open questions is whether AI will translate into genuine productivity gains across the broader economy. The information technology revolution and widespread internet adoption ultimately delivered a meaningful productivity boost, and that precedent matters. So far, the 2020s have seen average productivity growth of 2.1% per year, compared to just 1.2% during the 2010s. Whether AI and emerging technologies can sustain or accelerate this trend remains an open question with significant implications for markets and the economy in the years ahead.
Given these dynamics, maintaining a longer-term perspective remains essential. The largest technology companies today took decades to reach their current scale, even as markets showed considerable enthusiasm for the sector in the 1990s. Understanding how these trends interact with elevated interest rates and a renewed Fed rate hike cycle can help investors stay focused and disciplined through the final quarter of the year.
The bottom line
Stocks reached new highs in the third quarter, with many asset classes contributing to portfolios, despite bonds struggling as interest rates rise. As new developments unfold and the midterm election approaches, investors should continue to stay balanced and focus on financial goals.
Frequently asked questions
How did the stock market perform in Q3 2026?
The S&P 500 returned 2.3% in the third quarter of 2026 with dividends, the Nasdaq Composite gained 2.6%, and the Dow Jones Industrial Average declined 2.3%. Year-to-date through September 30, the three indices returned 12.7%, 16.1%, and 7.2%, respectively, and all three reached new all-time highs during the quarter.
Why did the Federal Reserve raise rates in September 2026?
The Fed raised its policy rate by a quarter of a percent to a range of 3.75% to 4.00%, its first increase in three years. The hike was largely a response to higher energy prices, a form of “cost-push inflation,” and was intended to keep elevated energy costs from spreading into other categories of inflation.
Are bonds still worth owning when interest rates are rising?
Rising rates pushed the Bloomberg U.S. Aggregate Bond Index down 3.5% in the third quarter, but they also mean bond yields are now at their most attractive levels in recent memory. With the 10-year Treasury yield near 5.29%, bonds can generate more meaningful income than they could during the low-rate years after 2008.
Do stocks perform poorly in midterm election years?
Not historically. The S&P 500 has averaged annual total returns of 8.6% in midterm election years since 1933, and markets have generally performed well across different configurations of Congress. Past performance is no guarantee of future results, but history suggests political headlines alone are not a reason to change a long-term investment plan.
How should investors approach the fourth quarter of 2026?
With interest rates, Fed policy, oil prices, and the midterm election all in play, the most important step is staying balanced and focused on long-term financial goals rather than reacting to short-term headlines. A diversified portfolio built to hold up across a range of economic and political environments matters more than predicting any single outcome.
What does this mean for your plan?
Every client’s situation is different, and market conditions like these affect each plan in its own way. If you have questions about how higher rates, the Fed, or the election season could affect your portfolio or long-term goals, reach out to schedule a conversation. You can also learn more about our approach to fee-only, conflict-free planning or browse more market commentary in our Resource Library.
References
1. Return figures represent total returns with reinvested dividends. All figures as of September 30, 2026
2. Clearnomics research using Federal Reserve data, as of September 30, 2026
3. Freddie Mac Primary Mortgage Market Survey
4. Clearnomics research using LSEG data, as of September 30, 2026
5. Clearnomics research using FTSE Russell and MSCI data, as of September 30, 2026
7. Clearnomics research using Standard & Poor’s data, as of September 30, 2026
8. Clearnomics research using Standard & Poor’s data, as of September 30, 2026
9. U.S. Treasury Fiscal Data: National Debt
10. U.S. Treasury Fiscal Data: National Deficit
11. Clearnomics research using LSEG and Standard & Poor’s data, as of September 30, 2026
Index Descriptions
S&P 500
The Standard & Poor’s 500 Index is a capitalization-weighted index of 500 stocks designed to measure performance of the broad domestic economy through changes in the aggregate market value of 500 stocks representing all major industries. The modern design of the S&P 500 stock index was first launched in 1957. Performance prior to 1957 incorporates the performance of the predecessor index, the S&P 90.
Dow Jones
The Dow Jones Industrial Average consists of 30 stocks that are major factors in their industries and widely held by individuals and institutional investors.
NASDAQ
The NASDAQ Composite Index measures all NASDAQ domestic and non-U.S. based common stocks listed on The NASDAQ Stock Market. The market value, the last sale price multiplied by total shares outstanding, is calculated throughout the trading day, and is related to the total value of the Index.
MSCI Emerging Markets Index
The MSCI EM (Emerging Markets) Index is a free float-adjusted market capitalization weighted index that is designed to measure the equity market performance of the emerging market countries of the Americas, Europe, the Middle East, Africa and Asia. The MSCI EM Index consists of the following emerging market country indices: Brazil, Chile, Colombia, Mexico, Peru, Czech Republic, Egypt, Greece, Hungary, Poland, Qatar, Russia, South Africa, Turkey, United Arab Emirates, China, India, Indonesia, Korea, Malaysia, Philippines, Taiwan, and Thailand.
MSCI EAFE Index
The MSCI EAFE Index is a free float-adjusted market capitalization index that is designed to measure the equity market performance of developed markets, excluding the US & Canada. The MSCI EAFE Index consists of the following developed country indices: Australia, Austria, Belgium, Denmark, Finland, France, Germany, Hong Kong, Ireland, Israel, Italy, Japan, the Netherlands, New Zealand, Norway, Portugal, Singapore, Spain, Sweden, Switzerland and the UK.
Bloomberg US Aggregate Bond Index
The Bloomberg U.S. Aggregate Bond Index is an index of the U.S. investment-grade fixed-rate bond market, including both government and corporate bonds.
DXY
The DXY is a U.S. dollar index based on a basket of currencies, including the Euro, Yen, Pound, Canadian Dollar, Swedish Krona and Swiss Franc.
All Content is information of a general nature and does not address the circumstances of any particular individual or entity. This Content is for informational purposes only; you should not construe any such information or other material as legal, tax, investment, financial, or other advice as a specific recommendation or specific endorsement by Columbus Street. The information in this document is provided in good faith without any warranty and is intended for the recipient’s background information only. Columbus Street accepts no responsibility for loss arising from the use of the information contained herein. In exchange for using this Content, you agree not to hold Columbus Street liable for any possible claim for damages arising from any decision you make based on information or other Content made available to you. You alone assume the sole responsibility of evaluating the merits and risks associated with using any information or other Content provided by Columbus Street before making any decisions based on such information or other Content. You should consult with your tax advisor and financial professional before making any determination as to the appropriateness of any planning strategy indicated herein.
Copyright (c) 2026 Clearnomics, Inc. All rights reserved. The information contained herein has been obtained from sources believed to be reliable, but is not necessarily complete and its accuracy cannot be guaranteed. No representation or warranty, express or implied, is made as to the fairness, accuracy, completeness, or correctness of the information and opinions contained herein. The views and the other information provided are subject to change without notice. All reports posted on or via www.clearnomics.com or any affiliated websites, applications, or services are issued without regard to the specific investment objectives, financial situation, or particular needs of any specific recipient and are not to be construed as a solicitation or an offer to buy or sell any securities or related financial instruments. Past performance is not necessarily a guide to future results. Company fundamentals and earnings may be mentioned occasionally, but should not be construed as a recommendation to buy, sell, or hold the company’s stock. Predictions, forecasts, and estimates for any and all markets should not be construed as recommendations to buy, sell, or hold any security, including mutual funds, futures contracts, and exchange traded funds, or any similar instruments. The text, images, and other materials contained or displayed in this report are proprietary to Clearnomics, Inc. and constitute valuable intellectual property. All unauthorized reproduction or other use of material from Clearnomics, Inc. shall be deemed willful infringement(s) of this copyright and other proprietary and intellectual property rights, including but not limited to, rights of privacy. Clearnomics, Inc. expressly reserves all rights in connection with its intellectual property, including without limitation the right to block the transfer of its products and services and/or to track usage thereof, through electronic tracking technology, and all other lawful means, now known or hereafter devised. Clearnomics, Inc. reserves the right, without further notice, to pursue to the fullest extent allowed by the law any and all criminal and civil remedies for the violation of its rights.
Keep more of what you earn. Do more of what you love.
Want to know more? Get in touch.
*Please do not send any financial information